Seven bankruptcies and an eighth looming: how Aston Martin became a "penny stock"
Aston Martin has already filed for bankruptcy seven times in 113 years. Between 1.21 billion pounds of debt, an emergency 550 million refinancing and the sale of its intellectual property, the Gaydon marque is fighting for financial survival while its sales rise 43%.
Seven bankruptcy filings in 113 years, and an eighth now openly discussed by analysts: Aston Martin's story looks less like an industrial trajectory than a repeated act of survival. Today, the stock trades as a penny stock, arguably the most brutal signal ever sent to a luxury car brand.
The case deserves a cool-headed reading, backed by figures. Because it says something broader: the difference between a desirable brand and a viable company. And because it explains, indirectly, why our relationship with the exceptional car is changing in nature.
The context: structural fragility, not a cyclical accident
The starting point is not cyclical. Aston Martin has already declared bankruptcy seven times. One hundred and thirteen years after its birth, the Gaydon marque has known only brief moments of respite, and even fewer profitable periods. It is now heading towards an eighth filing if nothing changes.
That is what sets it apart from a manufacturer merely weakened by a bad cycle: the company has almost never found its economic balance. The name is known worldwide, associated with James Bond, with Le Mans, with a certain idea of British grand touring. The balance sheet has been telling a different story for decades.
The current orders of magnitude: roughly 1.21 billion pounds of debt, an emergency refinancing of 550 million pounds, and a market value that has fallen to less than a tenth of the level recorded at the IPO. Over the same period, Ferrari posts 1.6 billion euros in net profit and Lamborghini 768 million euros in operating income. The same segment, two financial planets.
What exactly does the 550 million pound refinancing contain?
The deal that set the case alight is a complex structure, put together under pressure. The British manufacturer has just secured 550 million pounds sterling, roughly 735 million US dollars, led by HPS Investment Partners, an asset manager now part of BlackRock.
- A secured loan of 450 million pounds, drawn immediately.
- An additional loan of 100 million pounds, available at a later stage.
- Additional debt capacity, also capped at 100 million pounds.
- A rate set at 6.75% above SONIA, the British benchmark index.
- A maturity in July 2031.
SONIA plus 675 basis points is high-risk debt pricing. The reading is unambiguous: the market no longer lends to Aston Martin as it would to a luxury house, but as it would to a restructuring case. This financing buys time (until 2031), not profitability.
Why is the sale of intellectual property inflaming creditors?
This is where the case becomes legally explosive. To avoid suffocation, the manufacturer has sold 50.1% of its non-automotive intellectual property rights to Authentic Brands Group, the parent company of Reebok and Brooks Brothers. The majority of the licensing potential of the Aston Martin name outside cars therefore escapes its exclusive control.
It was not a first. Earlier this year, the brand had already raised 50 million pounds by transferring to AMR GP Holdings the rights to use its name by its Formula 1 team, a structure controlled by Lawrence Stroll, executive chairman and main shareholder. Selling your name piece by piece: the method says quite enough about the state of the cash position.
The response was immediate. Existing creditors, representing 1.3 billion pounds of claims, have sent a formal notice to the board of directors. Their argument: this intellectual property is a strategic asset that could serve as collateral in the event of liquidation. Legal proceedings could be launched to block the transaction.
The mechanism is well known to distressed debt specialists. Once certain subsidiaries are designated as unrestricted, they leave the security package granted to historic creditors and can raise new debt, sell assets or distribute dividends without their consent. Zonebourse compares the manoeuvre to Patrick Drahi's at Altice in November 2025, with one major nuance: at Aston Martin, it is head-on and immediate, whereas at Altice the scheme served as negotiating leverage.
The risk is explicit: this kind of operation, possibly life-saving in the very short term, means burning bridges with investors for a long time. You save a quarter, you mortgage a decade of financing.
"Penny stock": journalistic shorthand or market reality?
Market reality. The stock is a penny stock and the two bonds maturing in 2029 trade at distressed levels. Market value has fallen to less than a tenth of the IPO level. Caradisiac sums up the view from trading floors without mercy: the house is now a "negligible quantity for traders".
The balance sheet explains the rest. Enterprise value stands at 1.9 billion pounds, four fifths of which is made up of debt. In other words, the shareholder holds nothing more than a residual option on a company 80% owned by its creditors. This is no longer an industrial investment, it is a bet on a negotiation.
How can sales grow while losses widen?
This is the most counter-intuitive point of the case, and the most revealing. The commercial rebound is very real.
- 1,392 vehicles sold in the second quarter, up 43% year on year.
- Momentum driven in particular by the Valhalla, the brand's plug-in hybrid.
- Revenue up 62%, at 358.2 million pounds (418 million euros).
- An improvement in gross margin over the same period.
And yet the bottom line is deteriorating: the net loss widens by almost a third, to 90.1 million pounds (105 million euros). The explanation lies largely in soaring financial costs, notably an unfavourable currency effect on dollar-denominated debt.
This is the signature of a financial problem, not an industrial one: debt eats the margin faster than sales create it. The cars sell, the factory runs, desirability works, the balance sheet absorbs everything. Management remains upbeat: "We are on track to deliver a significant financial improvement this year compared with 2025," says Adrian Hallmark, chief executive. The comparison base is low: the 2025 annual results showed a 21% drop in revenue, to 1.26 billion pounds sterling.
Is the Valhalla enough to turn the equation around?
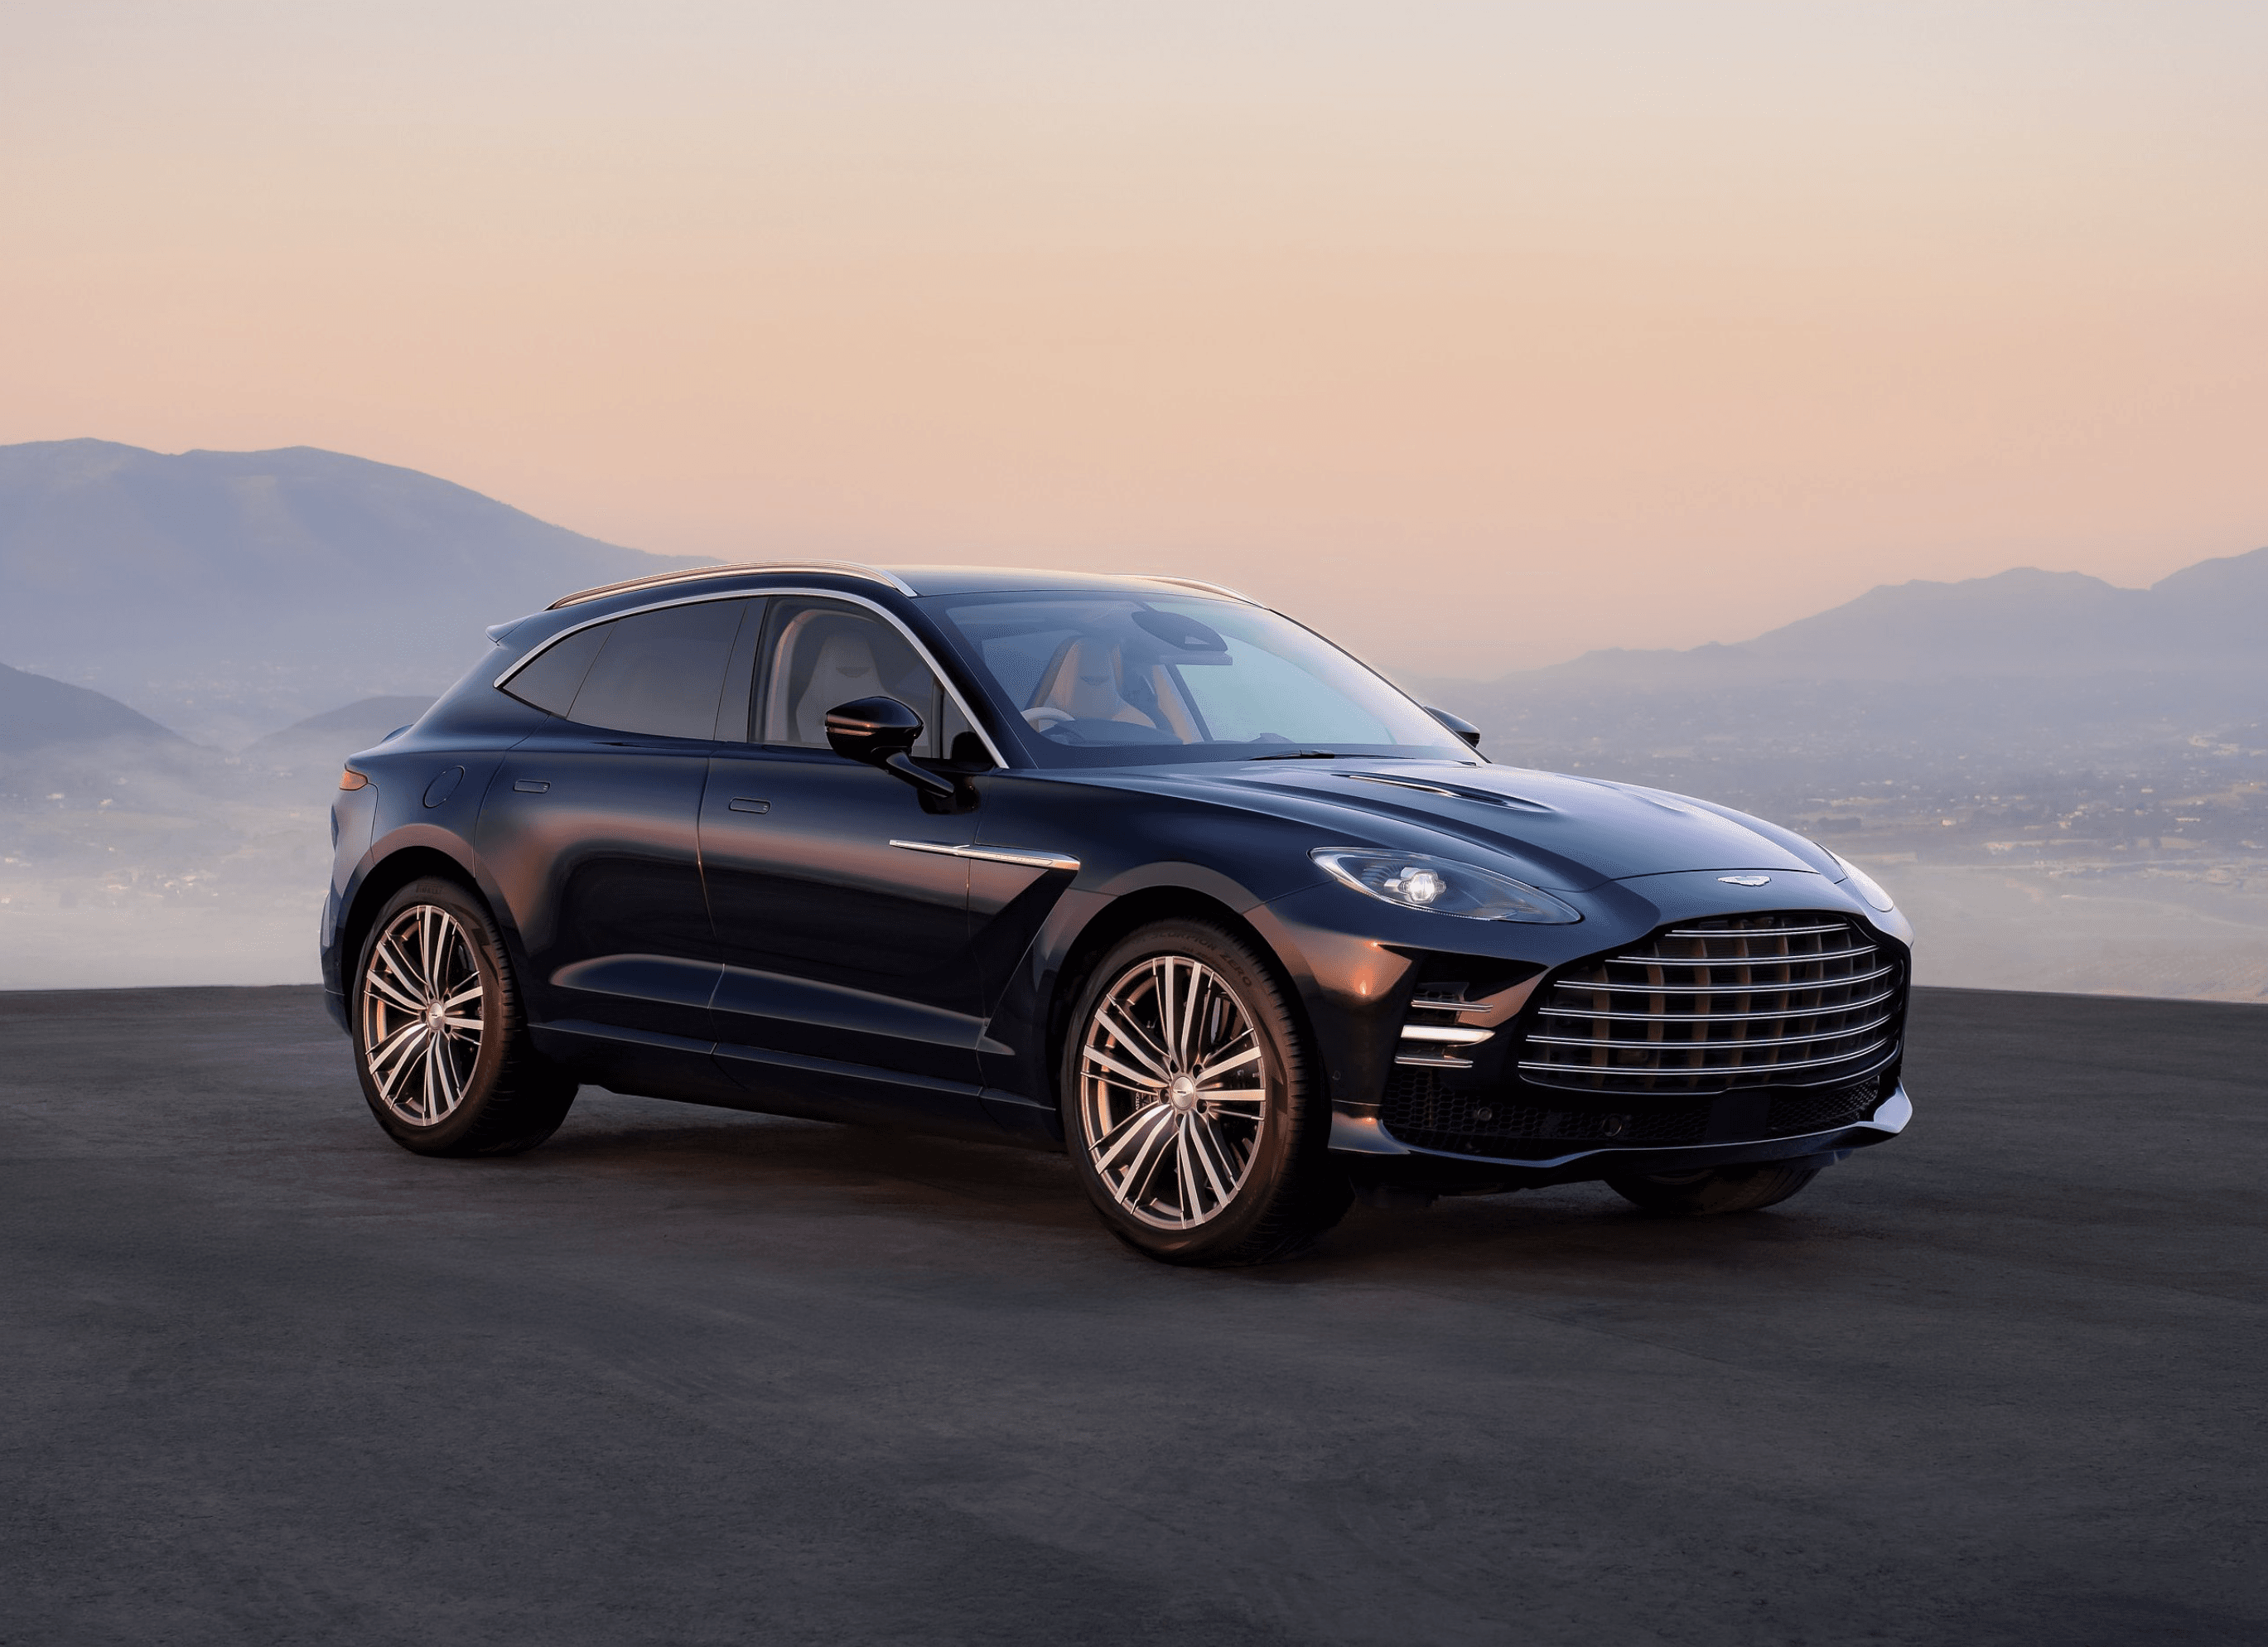
The Valhalla is the product weapon of the turnaround, and technically it delivers on its promises: a 4.0-litre twin-turbo V8 paired with three electric motors. The integrated rear electric motor works with the front motors and an electric drive unit for torque vectoring, with a 6.1 kWh high-voltage battery running at 400 volts and delivering up to 150 kW.
- Architecture: 4.0 l twin-turbo V8 paired with three electric motors (plug-in hybrid).
- Combined output: 1,064 hp (793 kW, or 1,079 PS).
- Torque: 1,100 Nm.
- 0 to 100 km/h: 2.5 seconds.
- Top speed: 350 km/h.
- Battery: 6.1 kWh, 400 V architecture, 150 kW.
- Transmission: 8-speed dual-clutch, all-wheel drive.
The problem is not the car, it is arithmetic. With 1,392 units sold in a quarter across all ranges, no single model can generate the cash flows needed to absorb 1.21 billion pounds of debt carrying a coupon indexed to SONIA plus 675 basis points. The Valhalla improves the mix and the gross margin. It does not rewrite the balance sheet.
What do Ferrari and Lamborghini say about Aston Martin's real position?
The most telling comparison is not dynamic, it is accounting. Three houses sell sports cars with very high unit value, to largely comparable clienteles. The results, however, are anything but comparable.
Aston Martin
Result: net loss of 90.1 million pounds (105 million euros) for the quarter, worsening by almost a third.
Quarterly revenue: 358.2 million pounds (418 million euros), up 62%.
Volumes: 1,392 vehicles, up 43%.
Debt: around 1.21 billion pounds, refinancing of 550 million at SONIA + 675 basis points.
Market status: penny stock, enterprise value of 1.9 billion pounds, four fifths of it debt.
2025 financial year: revenue down 21%, at 1.26 billion pounds.
Ferrari
Result: 1.6 billion euros in net profit.
Position: the profitability benchmark of the segment, valued as a luxury house rather than a manufacturer.
Reading: the absolute counter-model, with a balance sheet that funds the product instead of constraining it.
Lamborghini
Result: 768 million euros in operating income.
Position: backed by a global automotive group, which neutralises standalone financing risk.
Reading: in this segment, a solid industrial shareholder is worth as much as an order book.
Verdict: what should we conclude from the Aston Martin case?
The verdict is clear, and it is not about the product. Aston Martin builds desirable, technically credible cars, with sales up 43% over a quarter. The problem sits entirely below the operating line: 1.21 billion pounds of debt, refinanced at a distressed-case rate, which turns every euro of gross margin into financial expense.
The sale of 50.1% of the non-automotive intellectual property is the decisive symptom. When a luxury house monetises its name to fund day-to-day operations, it sells its most durable asset to buy months. And when 1.3 billion pounds of creditors threaten to go to court to block the transaction, the subject is no longer strategy but control.
Our reading: the eighth bankruptcy is not a certainty, it is now a credible and openly discussed scenario. The July 2031 maturity buys time, but expensive time. The way out will come neither from a hypercar nor from a strong commercial quarter: it will come from massive deleveraging or from an industrial shareholder able to absorb the liabilities, as Lamborghini has had.
What this changes for those who drive exceptional cars
There is a transferable lesson here, and it goes beyond Gaydon. An exceptional car is never just an object: it is an asset exposed to the health of its manufacturer, to its residual value, to the availability of after-sales service and to the strength of the network. A strained financial situation is paid for, sooner or later, in used-car values and in the owner's peace of mind.
That is precisely the purpose of car subscription. With Turismo, you drive a premium car without carrying the asset risk: no residual value to shoulder, no very long-term commitment to a model whose industrial environment can change within eighteen months. One monthly payment, all inclusive, and the freedom to change when the market changes. Discover the models available on Turismo subscription.
FAQ
How many times has Aston Martin gone bankrupt?
Seven times over its 113 years of existence. An eighth filing is now openly discussed given the level of debt and the cost of the refinancing.
Why is Aston Martin described as a "penny stock"?
Because the share trades at very low levels and its market value has fallen to less than a tenth of the IPO level. Enterprise value stands at 1.9 billion pounds, four fifths of which is debt: the shareholder holds nothing more than a residual option.
What exactly did Aston Martin sell to Authentic Brands Group?
50.1% of its non-automotive intellectual property rights, to Authentic Brands Group, the parent company of Reebok and Brooks Brothers. Earlier in the year, the brand had already transferred to AMR GP Holdings, a structure controlled by Lawrence Stroll, the rights to use its name by its Formula 1 team, for 50 million pounds.
Are Aston Martin's sales falling?
No, quite the opposite. In the second quarter, the brand sold 1,392 vehicles, up 43% year on year, for revenue up 62% at 358.2 million pounds. It is the net loss that is widening, to 90.1 million pounds, mainly because of financial costs and an unfavourable currency effect on dollar-denominated debt.
What are the specifications of the Aston Martin Valhalla?
A 4.0-litre twin-turbo V8 paired with three electric motors, for 1,064 hp (1,079 PS) and 1,100 Nm. It covers 0 to 100 km/h in 2.5 seconds and reaches 350 km/h. Its 6.1 kWh battery at 400 V delivers up to 150 kW, with an 8-speed dual-clutch transmission and all-wheel drive.
In summary
- Seven bankruptcies in 113 years, and an eighth now considered a credible scenario.
- An emergency refinancing of 550 million pounds (450 + 100, plus 100 of additional capacity) led by HPS Investment Partners, at SONIA + 675 basis points, maturing July 2031.
- 50.1% of the non-automotive intellectual property sold to Authentic Brands Group, contested by 1.3 billion pounds of creditors through a formal notice.
- A share traded as a penny stock, with an enterprise value of 1.9 billion pounds, 80% of it debt.
- Sales up 43% and revenue up 62%, but a net loss widening to 90.1 million pounds.
- On the other side: 1.6 billion euros in net profit at Ferrari, 768 million euros in operating income at Lamborghini.
The conclusion fits in one sentence: the product is not the problem, the balance sheet is. And that is exactly why ownership is no longer the only intelligent way to drive a premium car.
With a Turismo subscription, available in Luxembourg, Belgium, France and Switzerland, you get access to a premium car all inclusive: insurance, maintenance, roadside assistance and registration in a single monthly payment, with a term of your choice and no residual value risk. Compare the plans and book your model in a few minutes.
Hesitating between combustion, plug-in hybrid or fully electric? Talk to our team: they will guide you towards the plan suited to your real mileage and your intended term.
Sources(12)
- Après sept faillites, Aston Martin emprunte 735 millions – L'annuel de l'automobile
- Aston Martin a fait faillite sept fois. Voici pourquoi elle vient encore d'emprunter 735 millions de dollars | Roadstr
- Aston Martin joue les emprunteurs-voyous | Zonebourse
- Dépôt de bilan d'Aston Martin : la vraie raison | Garage des Dunes
- Pourquoi Ferrari et Lamborghini gagnent pendant qu’Aston Martin sombre ?
- With the Aston Martin share price at penny stock levels, should investors consider buying? | The Twelfth Magpie
- Aston Martin creuse ses pertes mais vend plus de voitures - 29/07/2026 à 10:51 - Boursorama
- Aston Martin monétise son nom pour financer son avenir - Luxury Tribune
- Aston Martin se fragmente pour survivre à 1,21 milliard de livres de dettes
- Aston Martin réduit sa perte grâce à de meilleures ventes et moins de frais financiers | AM Today
- Les problèmes d'endettement annulent les gains de revenus d'Aston Martin au premier semestre - Path to Park
- fr.tradingeconomics.com